Reserve Bank of Malawi outlines SACCOs regulatory priorities at the 2026 SACCO Lakeshore Conference, including risk-based supervision and new cybersecurity guidelines
27th September 2026, The Reserve Bank of Malawi (RBM) has told SACCO leaders that regulation and supervision have been key to the sector's growth over the past decade and a half. It also warned that this growth brings new risks that require stronger governance, better internal controls and responsible use of technology.
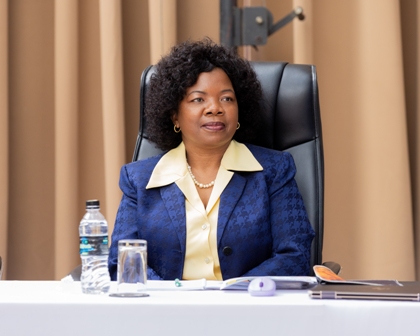
Mrs. Khumbo Mtalika - Director of Capital Markets and Microfinance Supervision presented on "Regulatory Trends" at the 2026 SACCO Lakeshore Conference. Her presentation looked at the compliance frameworks that protect members' funds and address emerging risks.
From reform to results
Mrs. Mtalika traced the sector's regulatory journey to a review of financial and regulatory systems that RBM began in August 2004. The review placed all banking and non-banking regulation under the central bank and created legal frameworks for each sector, including the Financial Cooperatives Act of 2011. She said the review was prompted by widespread fraud and governance lapses before 2011.
The figures she presented show how far the sector has come since 2012:
| Indicator | 2012 | 2026 (as of July) |
| Total assets | MK3.6 billion | MK180.1 billion |
| Deposits and shares | MK2.5 billion | MK100.0 billion |
| Loans | MK2.7 billion | MK120.0 billion |
| Capital ratio | 12.4% | 29.0% |
| Liquidity ratio | 8.9% | 24.0% |
| Delinquency ratio | 15.6% | 3.9% |
| Membership | 125,000 | 320,000 |
Growth brings new risks
Mrs. Mtalika cautioned that expansion can widen financial inclusion and member benefits but also increases exposure to several risks such as:
- Weak governance and oversight, as growth outpaces the capacity of boards and management.
- Technology and cybersecurity risks, including system failures, data breaches and third-party provider failures.
- Operational and internal control weaknesses, as new branches, staff and transaction volumes strain processes.
- Deterioration in loan books, where pressure to grow can weaken credit appraisal and collection.
- Liquidity risk, from higher loan demand, withdrawals or mismatched maturities.
- Compliance risk, as SACCOs expand into new products and locations.
- Climate-related risks, such as droughts and floods that impair members' ability to repay.
Regulatory priorities
RBM identified four priorities for addressing these risks and protecting member funds: effective risk management, strong governance, consumer protection and robust management information systems.
- Risk-based supervision. A SACCO Risk-Based Supervision Framework is being developed, with implementation targeted for the end of 2027. RBM says it will strengthen oversight, improve protection of members' funds and allow more efficient use of supervisory resources.
- Cybersecurity. Cybersecurity and Technology Risk Management Guidelines are planned for December 2027. Environmental, social and governance (ESG) regulatory and supervisory frameworks are also being developed.
- Governance. The Fit and Proper Directive is under review to raise governance standards. Boards are expected to provide effective strategic direction, risk governance and protection of members' funds.
- Consumer protection. Market conduct oversight will complement prudential supervision to promote fair treatment, transparency and member protection.
- Management information systems. MFI Hub Company, established in September 2017 to advance financial inclusion and digitise operations, is upgrading its system. RBM says such systems enable early detection of risks and effective oversight, and safeguard member information.
What SACCOs should focus on
Mrs. Mtalika outlined seven priority areas for SACCOs:
1. Institutional resilience: adequate capital and liquidity buffers and strong enterprise-wide risk management.
2. Governance: competent, accountable boards and management.
3. Internal controls and compliance: robust controls and a strong compliance culture.
4. Audit functions: independent and effective internal and external audits, with supervisory committees as alternative arrangements, and timely resolution of audit and regulatory findings.
5. Technology and cybersecurity: secure digital transformation, shared services for management information systems, and effective business continuity planning.
6. Skills and capacity building: continuous training for boards, management and staff, succession planning, and member education on savings, credit and digital services.
7. Protection of members' funds.
Call to action
Summing up, Mrs. Mtalika said regulation has driven SACCO growth and stability, and that sustainability depends on compliance, resilience and responsible innovation. She urged SACCOs to embrace compliance, strengthen governance, invest in risk management and use technology responsibly.